Starting a business with little or no money can be challenging, especially when you need funding for equipment, inventory, marketing, or other startup expenses. However, having limited personal savings does not automatically mean you cannot qualify for a business loan. Some lenders consider your credit history, business plan, projected revenue, and ability to repay the loan.
If you are wondering how to get a startup business loan with no money, the first step is to understand which financing options fit your situation. In the United States, options may include SBA-backed loans, nonprofit microlenders, community development financial institutions (CDFIs), and certain alternative funding programs. Each option has different eligibility requirements, costs, and repayment terms.
This guide explains how to explore startup business loans with no money, what lenders typically look for, which documents you may need, and what alternatives are available if your business has no revenue or you have limited credit history.
Can You Get a Startup Business Loan With No Money?
Yes, it may be possible to get a startup business loan with no money of your own, but approval depends on your financial situation, credit history, business plan, and ability to repay the loan. In the United States, some lenders work with new businesses that have limited operating history, although qualifying without personal savings, business revenue, or collateral can be more difficult.
Before applying, understand what “no money” means for your situation. Having no personal savings is different from having no business revenue or being unable to make a down payment. Each situation can affect your financing options differently.
What Does Having No Money Mean for Your Startup?
- No personal savings: You may still qualify for certain financing options if you have a solid business plan, suitable credit history, or another reliable way to demonstrate repayment ability.
- No business revenue: Approval may be more challenging because lenders have less evidence of your ability to generate cash flow and repay the loan.
- No down payment: Some financing programs may offer flexible down-payment requirements, depending on the lender, loan purpose, and your eligibility.
- No collateral: Certain loans do not require specific assets as security. However, a lender may still require a personal guarantee or assess your personal creditworthiness.
Which Startup Financing Options Can You Consider?
In the United States, you can explore SBA-backed loans through participating lenders, nonprofit microlenders, and Community Development Financial Institutions (CDFIs). One option is the SBA Microloan program, which provides loans of up to $50,000 through nonprofit intermediary lenders. These loans can help eligible small businesses pay for working capital, inventory, supplies, and equipment.
Another option is an SBA 7(a) loan, which can support eligible business purposes, including starting a business. However, applicants must satisfy the applicable eligibility requirements and demonstrate a reasonable ability to repay the loan.
Keep in mind that the SBA does not automatically approve every startup, and federal grants are generally not available simply because someone wants to start a business.
The bottom line: You do not necessarily need substantial personal savings to explore startup financing. Start by calculating how much money your business needs, preparing a realistic business plan, and comparing lenders’ eligibility requirements, interest rates, fees, and repayment terms before applying.
What Do Lenders Look for in a Startup With No Money?
When applying for a startup business loan in the United States, lenders want to understand whether your business has a realistic chance of succeeding and whether you can repay the borrowed amount. Even if you have little or no startup capital, preparing a strong application can help you demonstrate that you have a practical plan for managing the business.
Lenders may evaluate your personal credit history, business plan, expected cash flow, industry experience, existing debts, and available assets. The exact requirements vary by lender and loan program.
1. Personal Credit History
If your business is new and has not established its own credit history, lenders may rely heavily on your personal credit profile. They may review your credit score, payment history, outstanding debts, and how responsibly you manage existing credit accounts.
A stronger credit history may improve your financing options, while missed payments or high existing debt can make approval more difficult. However, credit requirements vary, and some nonprofit lenders may work with borrowers who have limited credit histories.
2. A Clear Business Plan
A business plan helps lenders understand what your startup will do, who your customers will be, and how the business intends to earn money. It should explain your products or services, target market, competitors, startup expenses, and expected sales.
If you have no money to invest initially, a realistic business plan becomes especially important. Include a clear explanation of how you will use the loan and why the amount requested is necessary.
3. Expected Cash Flow and Repayment Ability
Lenders need a reasonable basis to believe you can repay the loan. For a startup that has not generated revenue yet, they may examine projected sales, operating expenses, expected profit margins, and other available sources of repayment.
Prepare realistic financial projections rather than assuming your business will become profitable immediately. Include a plan for making payments if sales take longer than expected.
4. Personal or Business Assets
Some lenders require collateral to secure a loan. Depending on the financing arrangement, acceptable collateral may include equipment, vehicles, inventory, or other eligible assets.
If you do not have assets to pledge, you may need to focus on financing options that do not require specific collateral. Keep in mind that an unsecured loan may still require a personal guarantee, which can leave you personally responsible for the debt if your business cannot repay it.
5. Business and Industry Experience
Your experience can help demonstrate that you understand the business you want to launch. Lenders may consider previous work experience, industry knowledge, management skills, relevant qualifications, or experience operating a similar business.
If you are a first-time entrepreneur, explain how your skills, market research, business plan, and professional support will help you manage the business effectively.
6. Existing Debts and Financial Obligations
Lenders may review your personal debts, monthly expenses, and other financial commitments to assess whether you can handle additional loan payments.
Before applying, calculate your expected monthly repayment and compare it with your available income. Avoid borrowing more than your business realistically needs, particularly if revenue has not started.
7. How You Plan to Use the Loan
Lenders may ask for a detailed breakdown of how you intend to spend the funds. Common eligible business expenses may include equipment, inventory, supplies, working capital, or other costs permitted under the loan agreement.
A specific budget helps show that you have estimated your startup costs carefully and are requesting an appropriate amount.
Final takeaway: You do not always need substantial personal savings to explore startup financing, but having no money can make approval more challenging. A realistic business plan, responsible credit management, clear financial projections, and a credible repayment strategy can help you prepare a stronger application.
Best Startup Business Loan Options With No Money
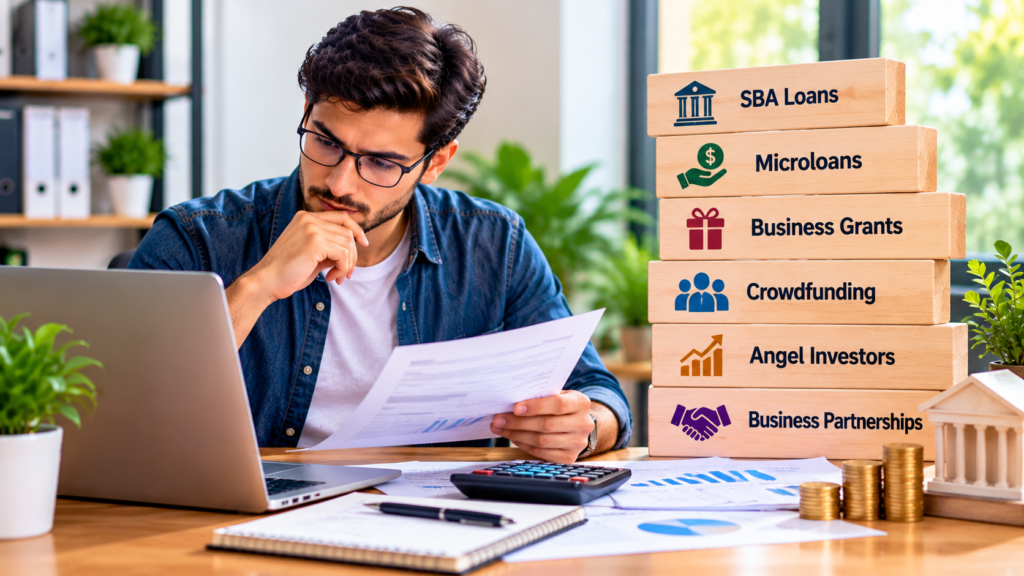
Starting a business in the United States without personal savings can make financing more challenging, but several funding options may be worth exploring. The right choice depends on how much money you need, whether your business has started generating revenue, your credit history, and your ability to repay the loan.
Before applying, compare the eligibility requirements, interest rates, fees, repayment terms, and collateral requirements of each option. No lender can guarantee approval simply because you have a business idea.
1. SBA Microloans
SBA Microloans can be a useful option for entrepreneurs who need a relatively small amount of startup funding. The U.S. Small Business Administration provides funds to nonprofit intermediary lenders, which make loans to eligible small businesses.
Eligible borrowers may receive up to $50,000, although the actual amount depends on the lender’s assessment. Funds can generally be used for working capital, inventory, supplies, furniture, and equipment. They cannot be used to purchase real estate or repay existing debt.
These loans may suit entrepreneurs who need a modest amount of money to launch or expand a business. However, each intermediary sets its own application requirements and evaluates the borrower’s ability to repay.
2. SBA 7(a) Loans
SBA 7(a) loans are designed to help eligible small businesses obtain financing through participating lenders. Depending on the loan and its approved purpose, funds may be used for working capital, equipment, supplies, or other eligible business expenses.
Although the program can support certain startup financing needs, qualifying may be difficult if your business has no revenue, no assets, and no demonstrated ability to repay the debt. Lenders assess your creditworthiness, business circumstances, and repayment capacity.
This option may be worth investigating if you have a well-developed business plan, strong financial projections, and a clear strategy for generating enough income to cover loan payments.
3. Community Development Financial Institutions (CDFIs)
Community Development Financial Institutions, commonly known as CDFIs, provide financial services to underserved communities and businesses that may face barriers to traditional financing.
Some CDFIs offer small-business loans, startup funding, financial education, and business counseling. Their eligibility requirements vary, and some focus on particular locations, industries, or borrower groups.
A CDFI may be worth considering if a conventional bank is unwilling to finance your startup. Contact a local organization to determine whether it supports pre-revenue businesses and whether you meet its lending requirements.
4. Nonprofit Microlenders
Nonprofit microlenders provide smaller loans to entrepreneurs who may not qualify for conventional business financing. Some also offer business training, mentoring, and assistance with preparing financial projections.
These lenders may consider your business plan, credit history, experience, and expected cash flow. However, nonprofit status does not automatically mean that a loan is interest-free or that approval is easy.
Compare the total borrowing cost, repayment schedule, fees, and any collateral or personal guarantee requirements before accepting an offer.
5. Equipment Financing
If your startup needs specific equipment, such as commercial kitchen appliances, computers, or manufacturing machinery, equipment financing may be an option.
With this type of financing, the equipment being purchased often serves as collateral for the loan. This can reduce the need to pledge other assets, although lenders may still require a down payment, credit checks, or a personal guarantee.
Equipment financing is most appropriate when you need money for eligible equipment rather than general startup expenses. Make sure the expected business income can support the payments.
6. Business Lines of Credit and Online Lenders
A business line of credit allows an eligible business to borrow up to an approved limit and draw funds when needed. Online lenders may also offer term loans or other financing products with different application requirements.
However, many of these providers prefer businesses with established revenue, regular bank deposits, or a track record of operations. A completely new business with no revenue may have fewer options.
Online financing can also be more expensive than some traditional alternatives. Review the annual percentage rate when available, fees, payment frequency, and consequences of missed payments before borrowing.
Which Startup Loan Option Should You Consider?
The most suitable option depends on your current situation.
- If you need less than $50,000: Investigate SBA Microloans and nonprofit microlenders.
- If you have a detailed business plan and strong repayment projections: Explore SBA-backed financing through participating lenders.
- If your business serves an underserved community: Check whether a CDFI offers a suitable startup loan.
- If you need to purchase equipment: Compare equipment financing offers.
- If your business already generates revenue: You may have additional options through banks, credit unions, and online lenders.
Remember that having no personal savings does not automatically disqualify you from every loan program. However, if you also have no revenue, limited credit history, and no collateral, it may be more practical to explore smaller funding options or alternatives before taking on debt.
How to Secure Startup Funding With Little or No Money
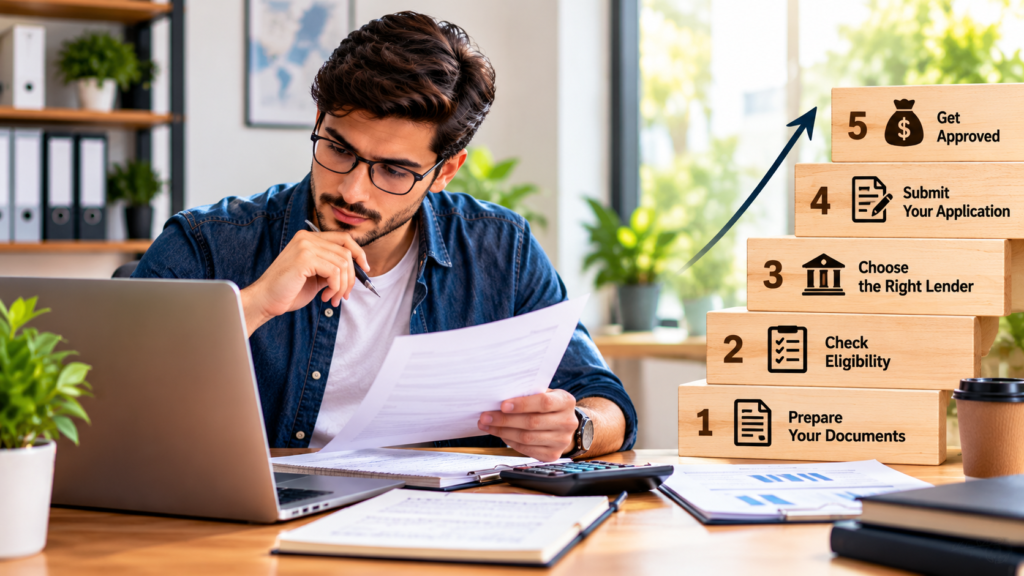
Getting a startup business loan with no personal savings can be challenging, but preparing carefully can help you identify suitable lenders and improve your application. In the United States, lenders may evaluate your personal credit, business plan, estimated startup costs, and ability to repay the loan. Requirements vary depending on the lender and financing program.
Follow these steps to prepare for startup financing.
Step 1: Calculate Your Startup Costs
Before applying for a loan, estimate how much money you need to launch your business. Include essential expenses such as equipment, inventory, licenses, insurance, marketing, rent, and working capital.
Separate one-time startup expenses from ongoing monthly costs. Organize your expected startup costs into categories such as equipment, inventory, marketing, and operating expenses.
For example, if you plan to start an online store, your budget might include website development, initial inventory, packaging, shipping supplies, and advertising. Look for expenses you can reduce before deciding how much financing to request.
Step 2: Prepare a Business Plan
A business plan explains what your business will sell, who your customers are, how you will compete, and how the business expects to generate income.
Include the following information:
- A description of your products or services.
- Your target customers and market research.
- Estimated startup and operating expenses.
- Expected sales and profit projections.
- Your marketing and customer acquisition strategy.
- A clear plan for repaying the loan.
If your business has not generated revenue yet, use realistic financial projections based on research rather than assuming immediate profits. A well-prepared plan can help lenders assess whether your business idea is financially viable.
Step 3: Check Your Personal Credit
Many startup owners have not yet established business credit. As a result, lenders may consider the owner’s personal credit history when reviewing an application.
Check your credit reports for errors, review outstanding debts, and make payments on time. If your credit history is limited or needs improvement, consider working on it before applying for financing.
Avoid submitting numerous applications without first checking eligibility requirements. Depending on the lender, a formal application may involve a hard credit inquiry that can temporarily affect your credit score.
Step 4: Research Suitable Startup Loan Programs
Compare financing options that may accommodate new businesses with limited capital. In the United States, potential options include SBA Microloans, SBA-backed loans through participating lenders, nonprofit microlenders, and Community Development Financial Institutions.
Each program has different eligibility criteria. Some lenders may work with businesses that have limited operating history, while others require established revenue, collateral, or a personal guarantee.
Before applying, confirm whether the lender accepts pre-revenue startups and ask about minimum credit requirements, down payments, interest rates, fees, and repayment terms.
Step 5: Gather the Required Documents
Preparing your documents in advance can make the application process easier. Depending on your business and lender, you may need:
- A detailed business plan.
- A startup cost estimate and financial projections.
- Personal identification and personal financial information.
- Personal and business credit information, where applicable.
- Business registration documents and required licenses.
- Bank statements, tax returns, or proof of income, if available or requested.
- Details of any collateral or personal guarantee.
A brand-new business may not have business tax returns or historical revenue records. Ask the lender which alternative documents it accepts rather than assuming you must provide records that do not yet exist.
Step 6: Compare Lenders and Submit Your Application
Once your documents are ready, compare several suitable lenders instead of accepting the first offer you receive.
Review the annual percentage rate (APR), interest rate, origination fees, repayment schedule, prepayment conditions, and any collateral or personal guarantee requirements. A loan with smaller payments may still cost more overall if the repayment period is longer.
For SBA-backed financing, you can explore participating lenders through the SBA’s Lender Match service. The SBA generally guarantees a portion of qualifying loans made by participating lenders; it does not directly approve every applicant or guarantee that you will receive funding.
Submit accurate information and answer the lender’s questions clearly. Never exaggerate projected revenue or provide misleading financial documents to improve your chances of approval.
Step 7: Review the Loan Offer Before Accepting
If a lender approves your application, read the loan agreement carefully before signing. Confirm the total amount borrowed, interest rate, fees, repayment dates, and consequences of missed payments.
Pay particular attention to personal guarantees. Depending on the agreement, you may remain personally responsible for repaying the debt even if your startup fails.
Be cautious of lenders or brokers promising guaranteed approval in exchange for an upfront fee. Verify the provider’s legitimacy and understand all costs before sharing sensitive financial information or agreeing to borrow.
Final takeaway: The best approach is to calculate your funding needs, build a realistic business plan, check your credit, and target lenders whose requirements fit your circumstances. If you have no savings and no business revenue, approval may be more difficult, so consider smaller financing options and alternatives that do not require taking on unaffordable debt.
Can You Get a Business Loan With No Revenue or Bad Credit?
Yes, it may be possible to get a business loan with no revenue or bad credit in the United States, but qualifying can be more difficult. Lenders want to understand how you will repay the borrowed money, especially when your business has not started generating income or your credit history has some problems.
Your available options depend on factors such as your personal credit history, business plan, industry experience, existing debts, collateral, and other sources of income. Some nonprofit lenders and community-based financing programs may consider applicants who do not meet traditional banks’ requirements.
Can You Get a Business Loan With No Revenue?
A startup does not always need an established revenue history to explore financing. Some lenders consider new businesses using their business plans, financial projections, personal credit, and expected ability to repay.
However, having no revenue makes approval more challenging because the lender cannot evaluate an established pattern of business income. You may need to demonstrate how the business will attract customers, generate sales, and cover loan payments.
Consider these potential options:
- SBA Microloans: These may help eligible startups finance working capital, inventory, supplies, or equipment. Approval depends on the intermediary lender’s requirements and your financial circumstances.
- Nonprofit microlenders: Some offer smaller loans and business support to entrepreneurs who have difficulty obtaining traditional financing.
- CDFIs: Community Development Financial Institutions may offer financing to eligible businesses in underserved communities.
- Equipment financing: If you need specific business equipment, financing secured by that equipment may be worth exploring, although a down payment or personal guarantee may still be required.
Is Business Financing Possible With a Low Credit Score?
Bad credit does not automatically eliminate every financing option, but it can limit your choices and increase borrowing costs. Lenders may review your credit score, payment history, existing debt, and the reasons behind past financial difficulties.
If your credit history is weak, consider the following steps before applying:
- Review your credit reports: Check for inaccurate information and dispute errors with the appropriate credit reporting agency.
- Reduce existing debt where possible: Lower outstanding balances and avoid taking on additional unaffordable obligations.
- Prepare a strong business plan: Explain your target market, startup expenses, expected revenue, and repayment strategy.
- Explore nonprofit lenders: Ask whether they consider borrowers with lower credit scores or limited credit histories.
- Consider a smaller loan: Requesting only the amount you need may make your financing plan more realistic.
Be careful with high-cost loans marketed to borrowers with poor credit. Review the APR, fees, repayment frequency, and personal guarantee requirements before signing an agreement.
What If You Have No Revenue and Bad Credit?
If your startup has no revenue and you also have bad credit, obtaining a conventional business loan may be particularly difficult. You may need to establish a stronger financial foundation before applying.
Depending on your circumstances, consider starting with a smaller business model, reducing initial expenses, building your credit history, or exploring crowdfunding and eligible grant programs. You could also seek support from a Small Business Development Center (SBDC) for help preparing a business plan and understanding financing options.
A co-signer or guarantor may help with some financing arrangements, but only if the lender permits it and the person meets its requirements. A personal guarantee can create significant financial responsibility, so make sure everyone understands the risks.
The bottom line: You may be able to obtain startup financing with no revenue or bad credit, but approval is not guaranteed. Focus on realistic financial projections, affordable funding options, and lenders whose eligibility requirements match your situation. Avoid borrowing money that your business has no reasonable plan to repay.
What Documents Do You Need for a Startup Business Loan?
When applying for a startup business loan in the United States, lenders typically ask for documents that help them verify your identity, understand your business, evaluate your financial situation, and assess your ability to repay the loan. The exact requirements depend on the lender, loan amount, and financing program.
If your business is brand-new and has no revenue, you may not have business tax returns or historical financial statements. In that case, lenders may focus more on your business plan, startup budget, financial projections, personal credit history, and other available evidence of repayment ability.
1. Business Plan
A business plan explains what your startup will do, who your customers are, and how you intend to generate revenue. It should describe your products or services, target market, competitors, marketing strategy, and business goals.
Include a clear explanation of how you will use the loan. Lenders need to understand why you need the requested amount and how the funding will support your business.
2. Startup Budget and Financial Projections
Prepare a detailed estimate of your initial expenses, including equipment, inventory, licenses, insurance, marketing, and working capital.
Your financial projections should estimate future sales, operating costs, cash flow, and expected profits. Use reasonable assumptions based on market research rather than overly optimistic figures.
If you have no business revenue yet, these projections can help explain how you expect to generate enough cash to cover future loan payments.
3. Personal Identification and Financial Information
Lenders generally need to verify your identity and may request personal financial information. Depending on the application, this may include government-issued identification, your Social Security number or other applicable taxpayer identification number, proof of address, and information about your personal income and existing debts.
If you are applying as a business owner in the United States, make sure the information you provide matches your official records.
4. Personal and Business Credit Information
Many startup lenders review the owner’s personal credit history because a new business may not have an established credit profile.
You may be asked to authorize a credit check and provide details about existing loans, credit card balances, and other financial obligations. If your business already has a credit history, the lender may also review its business credit information.
A strong credit history can help, but the minimum requirements vary among lenders and loan programs.
5. Business Registration Documents
Depending on your business structure and the lender’s requirements, you may need documents such as:
- Articles of incorporation or organization.
- Business registration records.
- An Employer Identification Number (EIN), if applicable.
- Required business licenses and permits.
- An operating agreement or partnership agreement, if applicable.
A sole proprietor may not need the same documents as an LLC or corporation. Confirm which records apply to your business before submitting your application.
6. Bank Statements and Tax Returns
Lenders may request personal or business bank statements to understand your available funds, income, and financial activity. Established businesses may also need to provide business tax returns and financial statements.
A new startup without revenue may not have business tax returns or several months of business bank statements. Ask the lender whether it accepts alternative documentation, such as personal financial records, current bank statements, or financial projections.
Never create or alter financial records to make your application appear stronger.
7. Collateral and Personal Guarantee Documents
Some business loans require collateral, such as eligible equipment, vehicles, inventory, or other assets. If collateral is required, the lender may ask for information establishing ownership and value.
Some lenders may also require a personal guarantee, which can make you personally responsible for the debt if your business fails to repay it.
Not every startup loan requires specific collateral, but you should understand any personal obligations before signing the agreement.
8. Additional Documents for SBA Loans
If you apply for financing through a participating lender under a Small Business Administration (SBA) program, you may need additional information based on the specific loan and your circumstances.
This may include ownership details, business financial information, personal financial statements, information about how the funds will be used, and other eligibility documents requested by the lender.
Requirements differ between SBA loan programs and participating lenders, so do not assume that every applicant must submit an identical set of forms.
Final takeaway: Preparing your documents before applying can make the startup loan process easier and help you identify missing information early. If you have no revenue yet, focus on a detailed business plan, a realistic startup budget, and credible financial projections. Always confirm the final document requirements with your chosen lender before submitting your application.
How to Improve Your Chances of Loan Approval
Getting approved for a startup business loan with no money can be challenging, especially if your business has no revenue or limited credit history. However, preparing a strong application, choosing the right lender, and demonstrating how you plan to repay the loan can help strengthen your chances of approval.
In the United States, lenders have different eligibility requirements, so focus on options that match your financial situation and business goals.
1. Prepare a Strong Business Plan
A clear business plan helps lenders understand how your startup will operate and generate income. Explain what your business offers, who your customers are, how you will attract them, and what makes your business competitive.
Include realistic sales forecasts, startup expenses, operating costs, and a repayment strategy. Support your estimates with market research wherever possible.
2. Improve Your Personal Credit History
Many lenders consider an owner’s personal credit history when evaluating a new business that has not established business credit.
Review your credit reports for errors, pay existing bills on time, and reduce outstanding balances when possible. Avoid taking on additional debt that you cannot comfortably manage.
If your credit history is limited, look for lenders whose requirements fit your circumstances rather than applying indiscriminately.
3. Borrow Only What Your Business Needs
Requesting an appropriate loan amount can make your funding plan more credible. Calculate the cost of essential equipment, inventory, licenses, marketing, and working capital before deciding how much to borrow.
Avoid requesting extra money without a clear purpose. A realistic budget helps explain how the funds will support your business and how you expect to manage repayments.
4. Demonstrate How You Will Repay the Loan
Lenders want to understand where the repayment money will come from. If your startup has no revenue yet, prepare financial projections showing your expected sales, expenses, cash flow, and estimated time to reach profitability.
Be realistic about how long it may take to attract customers and generate income. If you have another legitimate source of income, the lender may consider it when assessing your financial circumstances.
Never rely solely on optimistic sales forecasts to justify borrowing.
5. Choose the Right Lender and Loan Program
Not every lender is suitable for a business with no startup capital. Compare banks, credit unions, SBA-backed financing through participating lenders, nonprofit microlenders, and Community Development Financial Institutions (CDFIs).
Before applying, ask whether the lender considers pre-revenue startups and review its credit, collateral, down-payment, and documentation requirements.
Choosing a lender whose eligibility criteria fit your situation can help you avoid unnecessary applications and unsuitable loan offers.
6. Organize Your Application Documents
Missing or inconsistent documents can delay the application process. Prepare your business plan, startup budget, financial projections, identification, and any registration or financial records the lender requests.
If your business is new and does not have tax returns or business bank statements, ask which alternative documents the lender accepts.
Make sure the information in your application matches your supporting records.
7. Consider Collateral or a Personal Guarantee Carefully
Some lenders may consider collateral or require a personal guarantee when evaluating startup financing. These arrangements can affect the lender’s assessment, but they also create financial risks for you.
Before agreeing, understand which assets could be at risk and whether you would remain personally responsible for repayment if the business fails.
Do not pledge essential personal assets unless you fully understand the consequences.
8. Explore Business Support Programs
Small Business Development Centers (SBDCs) and other business support organizations in the United States may provide guidance on business planning, financial projections, and financing applications.
Working with an adviser can help you identify weaknesses in your application and understand which funding options may be appropriate for your startup.
Some nonprofit lenders also offer business education or mentoring alongside financing.
Final takeaway: To improve your chances of startup loan approval, prepare a realistic business plan, strengthen your credit where possible, calculate your funding needs carefully, and choose lenders whose requirements match your circumstances. Approval is never guaranteed, but a well-prepared application can help you make a more informed financing decision.
Alternatives to Business Loans When You Have No Money
If you cannot qualify for a startup business loan in the United States, or you want to avoid taking on debt, several alternative funding options may help you launch your business with limited personal savings. The right choice depends on your business idea, funding needs, eligibility, and willingness to share ownership or seek outside support.
Before choosing an option, consider how much money you need, how quickly you need it, and whether you can manage the financial risks involved.
1. Small Business Grants
Small business grants provide funding that generally does not need to be repaid if you meet the program’s conditions. However, grants are often competitive and may be restricted to specific industries, locations, research projects, or eligible groups.
Research state and local economic development programs, nonprofit organizations, and industry-specific funding opportunities. Read the eligibility requirements carefully and avoid companies that promise guaranteed grants in exchange for upfront fees.
Do not assume that the federal government offers free grants to everyone who wants to start a business.
2. Crowdfunding
Crowdfunding allows you to raise money from multiple people through an online platform. It can be useful if your product or business idea appeals to a clearly defined audience.
Depending on the campaign structure, you might offer rewards, accept donations, or raise investment capital. Each approach has different legal requirements, costs, and obligations.
To improve your campaign, explain your business idea clearly, set a realistic funding target, and show potential supporters how the money will be used.
3. Angel Investors
Angel investors are individuals who invest their own money in certain startups in exchange for an ownership stake or another agreed investment arrangement.
This option may suit businesses with strong growth potential, a promising product, or a scalable business model. However, investors typically expect a credible business plan, evidence of market demand, and a potential return on their investment.
You may also need to share decision-making power or give up part of your ownership. Review any investment agreement carefully before accepting funds.
4. Friends and Family Funding
Friends or family members may be willing to help finance your startup when traditional lenders are unavailable. Depending on the arrangement, their contribution may be a gift, a loan, or an investment in the business.
Put the terms in writing, including the amount provided, repayment expectations, interest if applicable, and any ownership rights. Clear agreements can help prevent misunderstandings and protect personal relationships.
Only accept money that both parties understand and can afford to risk.
5. Start Small and Reinvest Your Earnings
If you have little or no startup capital, consider launching a smaller version of your business before investing in a larger operation.
For example, you might start a service-based business from home, sell products in small quantities, use free or low-cost business tools, or test demand before purchasing substantial inventory.
Once the business begins earning money, reinvest a portion of the profits into equipment, marketing, inventory, or expansion. This approach can reduce the amount of outside funding you need, although it may take longer to grow.
6. Business Partnerships
A business partner may contribute money, equipment, industry knowledge, or other resources in exchange for an agreed share of the business.
A partnership can reduce the amount of cash you personally need to contribute, but it also means sharing ownership, responsibilities, and potentially profits.
Before starting together, agree on each person’s role, financial contributions, decision-making authority, ownership percentage, and how disputes or a partner’s departure will be handled.
7. Business Incubators and Accelerators
Business incubators and accelerators support selected startups through mentoring, training, networking, and sometimes access to funding or investors.
Some programs charge fees or take an ownership stake, while others offer support without requiring equity. Availability and eligibility vary by location, industry, and program.
These programs may be especially useful if you need help developing your business model, validating your idea, preparing a pitch, or meeting potential investors.
Which Alternative Is Best for Your Startup?
The most appropriate option depends on your circumstances:
- If you want to avoid debt: Explore eligible grants, crowdfunding, or equity investment.
- If you have a promising product: Consider crowdfunding or approaching suitable angel investors.
- If you can start with minimal expenses: Launch a smaller version of the business and reinvest your earnings.
- If you have a reliable potential partner: Consider a written partnership agreement.
- If you need guidance as well as funding: Look into business incubators, accelerators, or small business mentoring programs.
Final takeaway: You do not always need a traditional business loan to start a company. Depending on your business idea and eligibility, grants, crowdfunding, investors, partnerships, or a low-cost launch strategy may help you move forward with limited savings. Compare the costs, obligations, and risks of each option before making a decision.
Common Mistakes to Avoid When Applying for a Startup Loan
Applying for a startup business loan without personal savings can be challenging, particularly if your business has no revenue or limited credit history. In the United States, avoiding common application mistakes can help you prepare a stronger application, compare financing options, and reduce unnecessary financial risks.
1. Applying Without a Clear Business Plan
A business idea alone may not be enough to convince a lender to provide financing. Lenders often want to understand your target market, startup expenses, expected sales, and repayment strategy.
Prepare a business plan that explains how your company will operate, attract customers, and generate income. Include realistic financial projections rather than assuming your business will become profitable immediately.
2. Requesting More Money Than You Need
Borrowing more than your startup requires can increase interest costs and make repayments harder to manage.
Calculate your essential startup expenses, including equipment, inventory, licenses, marketing, and working capital. Request an amount that matches your actual needs and explain how you intend to use the funds.
3. Ignoring Your Personal Credit History
Many lenders review the owner’s personal credit history when evaluating a new business without an established credit profile.
Before applying, review your credit reports, check for errors, pay bills on time, and reduce outstanding balances where possible. Avoid submitting multiple applications without checking eligibility, because some lenders may perform hard credit inquiries.
4. Overestimating Future Revenue
Overly optimistic sales projections can make your business plan less credible. If your startup has no revenue yet, lenders may pay particular attention to how you calculated your expected income and expenses.
Use market research, competitor analysis, realistic pricing, and estimated customer demand to support your projections. Include a plan for covering loan payments if sales take longer than expected.
5. Ignoring Interest Rates and Additional Fees
A loan with an attractive advertised rate may still be expensive once fees and repayment conditions are considered.
Before accepting an offer, review the annual percentage rate (APR), origination fees, repayment schedule, prepayment conditions, and total borrowing cost. If a lender quotes a factor rate rather than an interest rate, make sure you understand the actual dollar cost of borrowing.
Compare several suitable offers instead of choosing the first one available.
6. Applying to Lenders That Do Not Fit Your Situation
Not every lender finances businesses that have no revenue, limited credit history, or no collateral. Applying without checking the requirements can waste time and may lead to unnecessary credit inquiries.
Research SBA-backed financing, nonprofit microlenders, Community Development Financial Institutions (CDFIs), and other suitable providers. Ask whether they consider pre-revenue startups and confirm their eligibility criteria before submitting a formal application.
7. Submitting Incomplete or Inaccurate Documents
Missing documents can delay an application, while inconsistent or misleading information can damage your credibility.
Prepare your business plan, startup budget, financial projections, identification, and any business registration or financial records requested by the lender. If your company is new and does not have tax returns or business bank statements, ask whether alternative documents are acceptable.
Always provide truthful and accurate information.
8. Overlooking Personal Guarantees and Collateral Risks
Some startup loans require collateral or a personal guarantee. These arrangements can create serious financial obligations if your business cannot repay the debt.
Before signing, understand which assets may be at risk and whether you could be personally responsible for the outstanding balance. Do not assume that forming an LLC automatically protects you from obligations under a personal guarantee.
9. Falling for Loan Scams
Be cautious of lenders or brokers promising guaranteed approval regardless of your credit history or business finances. Requests for upfront fees in exchange for guaranteed funding can be a warning sign of fraud.
Verify the lender’s identity, review the loan agreement, and understand all charges before sharing sensitive information. Never pay an unfamiliar provider simply because it claims to have special access to guaranteed business loans.
10. Borrowing Without a Repayment Plan
Getting approved for a loan does not necessarily mean the debt is affordable. A startup may take months to generate consistent income, and loan payments can create financial pressure before the business becomes profitable.
Estimate your monthly payments and consider how you would manage them if revenue falls below expectations. If repayment depends entirely on uncertain future sales, consider reducing your startup costs or exploring funding alternatives before borrowing.
Final takeaway: Avoiding these mistakes can help you make better financing decisions when applying for a startup business loan in the United States. Focus on a realistic business plan, accurate documents, suitable lenders, transparent loan terms, and a repayment strategy you can reasonably manage. Approval is never guaranteed, so choose financing based on your actual needs and financial capacity.
Final Thoughts
Getting a startup business loan with no money in the United States can be challenging, but having limited personal savings does not automatically mean you cannot explore financing options. The right approach depends on your credit history, business plan, funding needs, and ability to repay the loan.
Start by calculating your startup expenses, preparing realistic financial projections, and researching suitable options such as SBA-backed loans, nonprofit microlenders, and Community Development Financial Institutions (CDFIs). If borrowing is not practical for your situation, consider alternatives such as crowdfunding, eligible grants, business partnerships, or launching on a smaller budget.
Before accepting any financing offer, compare interest rates, fees, repayment terms, and personal guarantee requirements. Avoid borrowing more than your business can reasonably afford to repay.
Ultimately, the best way to pursue startup funding is to prepare carefully, choose financing that fits your circumstances, and build your business on a realistic financial plan.
Frequently Asked Questions
Q1. Can I get a startup business loan with no money down?
A: Yes, some lenders may offer startup financing without requiring a down payment, but approval depends on your credit history, business plan, financial circumstances, and the loan program. You may still need to meet other eligibility requirements or provide a personal guarantee.
Q2. Can I get a startup loan with no revenue?
A: Yes, some lenders consider businesses that have not generated revenue yet. They may evaluate your business plan, financial projections, personal credit, and ability to repay the loan. However, having no revenue can make approval more difficult.
Q3. Can I get a business loan with bad credit and no money?
A: It may be possible, but your options could be limited. Some nonprofit microlenders and community development financial institutions consider applicants who have difficulty qualifying for traditional loans. Compare eligibility requirements and borrowing costs before applying.
Q4. Does the SBA give startup loans directly?
A: The U.S. Small Business Administration generally supports eligible business financing through participating lenders rather than lending directly to most borrowers. SBA-backed programs have specific eligibility requirements, and approval is not guaranteed.
Q5. Are there grants to start a business in the USA?
A: Some grants are available to eligible businesses through specific government programs, nonprofit organizations, and private initiatives. However, grants are often competitive and may have restrictions on how funds can be used. There is no general federal grant available to everyone simply for starting a business.
Q6. Can I get a startup business loan without collateral?
A: Some lenders offer loans that do not require specific collateral, but they may still assess your creditworthiness, income, and repayment ability. A personal guarantee may also be required, so review the loan terms carefully before signing.
Q7. What credit score do I need for a startup business loan?
A: There is no single credit score requirement for every startup business loan. Requirements vary by lender, loan program, and financing type. Some lenders may consider additional factors, such as your business plan, financial history, and available repayment resources.